
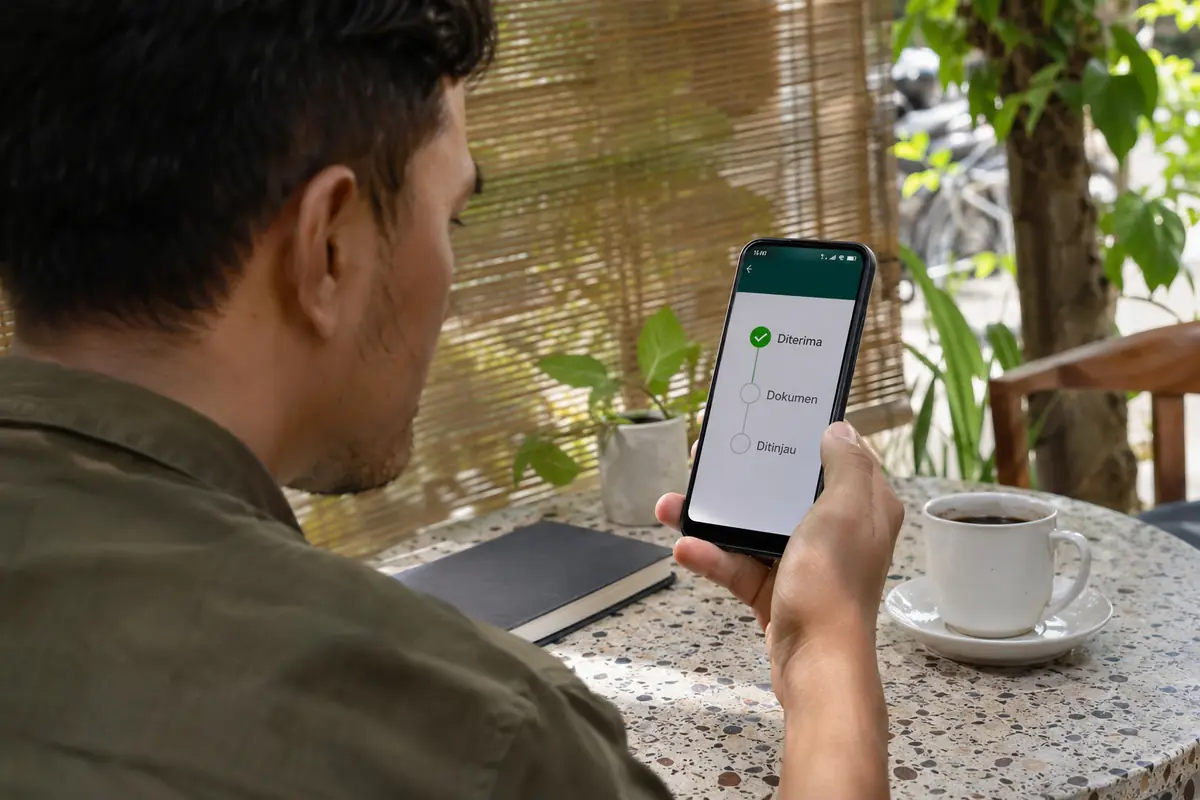
In Indonesia, a loan app with fast approval timelines promises a decision within minutes or hours instead of the days a branch visit used to need. The speed comes from automation: identity matching, credit record lookups and scoring models run in the background while the borrower waits. Real timing still varies by lender, loan size, document quality and the hour of the day. Licensed platforms advertise ranges rather than guarantees, and a promise of instant approval without any checks is a common marker of illegal lending that should make a borrower stop.
What approval actually means
Approval is a lender's internal decision that the applicant meets its criteria and may borrow up to a stated limit. It is a different event from disbursement, which is the transfer of money, and from the signing of the electronic agreement that sits between them.
Apps often blur these steps. A screen that says approved may refer only to a preliminary limit, with final confirmation still depending on a bank transfer check or a call to verify details. Reading the status wording carefully avoids false expectations. Screenshots of each status screen are useful records if a dispute arises later.
For a borrower, the useful number is the total time from submitting the application to receiving funds, since it is that period which determines whether the money arrives before a bill is due.
Typical timelines by product type
Speed differs sharply by product. Small unsecured cash loans from licensed apps are the quickest, with some platforms stating that decisions can arrive within minutes and others describing a processing window of up to one or two working days. Instalment shopping credit at checkout is similar, since the limit is often pre-approved.
Larger personal loans, multi-month instalment products and productive business loans take longer because they need more documents and sometimes human review. Mortgage-style and vehicle loans from banks and finance companies run to days or weeks, as they involve valuation, legal checks and signing in person.
Where a platform publishes a maximum processing time in its terms, that statement is the one to rely on rather than advertising slogans.
Factors that shorten the wait
Several habits make a decision come faster, and they are mostly within the borrower's control.
- Complete, readable documents uploaded in one session, with name and number matching across ID, phone and bank account.
- A previous record with the same lender, since returning borrowers often get shorter reviews and higher limits.
- A clean credit record, which lets the scoring model approve without escalation.
- Application during working hours, when manual checks are staffed.
A request that is plainly within the product's rules rarely needs human attention, which is what keeps it quick.
Factors that slow an application
Delays usually come from a short list of causes. Blurry photos, a selfie that fails the liveness check and mismatched names send an application to manual review. A credit record with complications, such as old overdue accounts, triggers extra analysis.
Bank-side issues matter too. An inactive account, a name that differs from the identity record or an outage in the interbank network can hold up the final transfer even after approval has been granted.
Peaks in demand, such as the days before major holidays or the end of the month, lengthen queues at lenders that still use partial manual processing. Applying earlier in the month and avoiding the last hours before a deadline gives more room. Lenders also retry failed identity checks only a limited number of times, so repeated attempts in a single evening can lock the account for a while.
How to read speed claims safely
Marketing language such as instant, in five minutes or without survey describes the best case for a well-prepared borrower. It does not describe what every applicant gets, and licensed platforms are expected to present information that is not fictitious or misleading.
The more important test is what happens before money is released. A legitimate lender verifies identity, checks the applicant and presents the full cost and the repayment schedule. If an app claims approval without any verification, or asks for a payment to release the loan, the speed is a lure.
A fast decision should never remove the borrower's chance to read the cost. Interest, administration fees and late charges must be visible before agreeing, and a short delay to compare them is cheap protection.
Speed versus cost and risk
Quick access to money tends to come with a price. Short-tenor cash loans usually carry higher effective cost than a bank personal loan, and OJK sets limits on the maximum economic benefit per day and reviews them periodically. Even within those limits, a small amount repaid within weeks can show a high annualised rate.
The temptation of rapid approval is also a behavioural risk. Easy money encourages borrowing for needs that could wait, and stacking several loans from different apps leaves repayment dates piling up in the same week.
A practical approach is to treat the speed as a feature for genuine emergencies and to use slower, cheaper sources, such as a bank loan or a cooperative, when the need is planned.
Timing across days, hours and banks
Clock and calendar affect the outcome. Automated decisions run at any hour, but steps that need staff, such as a verification call, follow office hours. A request filed late on a Friday may therefore wait until Monday for that step.
Money movement has also become faster. Transfers between banks can now run around the clock through the national fast payment system, yet the receiving bank, an e-wallet provider or a lender's own batching routine may still add a delay.
Borrowers who need funds by a fixed date should apply several days ahead, keep the phone available for verification calls and watch for messages instead of repeatedly resubmitting, since duplicate requests can slow everything down.
When approval takes longer than stated
If a request stays pending far beyond the lender's stated window, the first step is checking the status inside the app and the registered email for messages asking for additional documents. Many delays end as soon as a missing file is supplied.
The second step is contacting the lender's customer service through the channels listed in the official app or on its verified website, not through numbers sent in unsolicited messages.
Unresolved complaints can go to OJK at 157 or by WhatsApp at 081157157157. A borrower who has not accepted any agreement can simply withdraw and apply elsewhere, but one who has already signed should keep copies of all messages and receipts.
Frequently asked questions
How long does a licensed loan app usually take to approve a request?
Small unsecured loans can be decided within minutes to a couple of working days, depending on the platform. Larger or business loans take longer. The maximum processing time stated in the lender's terms is the reliable figure.
Is approval the same as receiving the money?
No. Approval is the lender's decision. Signing the electronic agreement and the bank transfer come afterwards, and each can add time.
Why is my application still pending?
Common reasons are unclear documents, a failed liveness check, name mismatches or a credit record that needs extra review. Checking the app status and the registered email usually shows what is missing.
Is an instant approval without checks a good sign?
No. Legitimate lenders verify identity and assess ability to repay. Instant approval with no checks, or a fee demanded before release, points to illegal lending.
Who can I contact if a lender takes far too long?
Start with the lender's official customer service. If that fails, OJK handles consumer complaints at 157 and on WhatsApp 081157157157.
Further reading
- AdaKami (page in Indonesian; English version not found) : Platform pinjaman daring berizin OJK yang menyebut pengajuan diproses paling lama 48 jam dan menampilkan biaya sejak awal.