
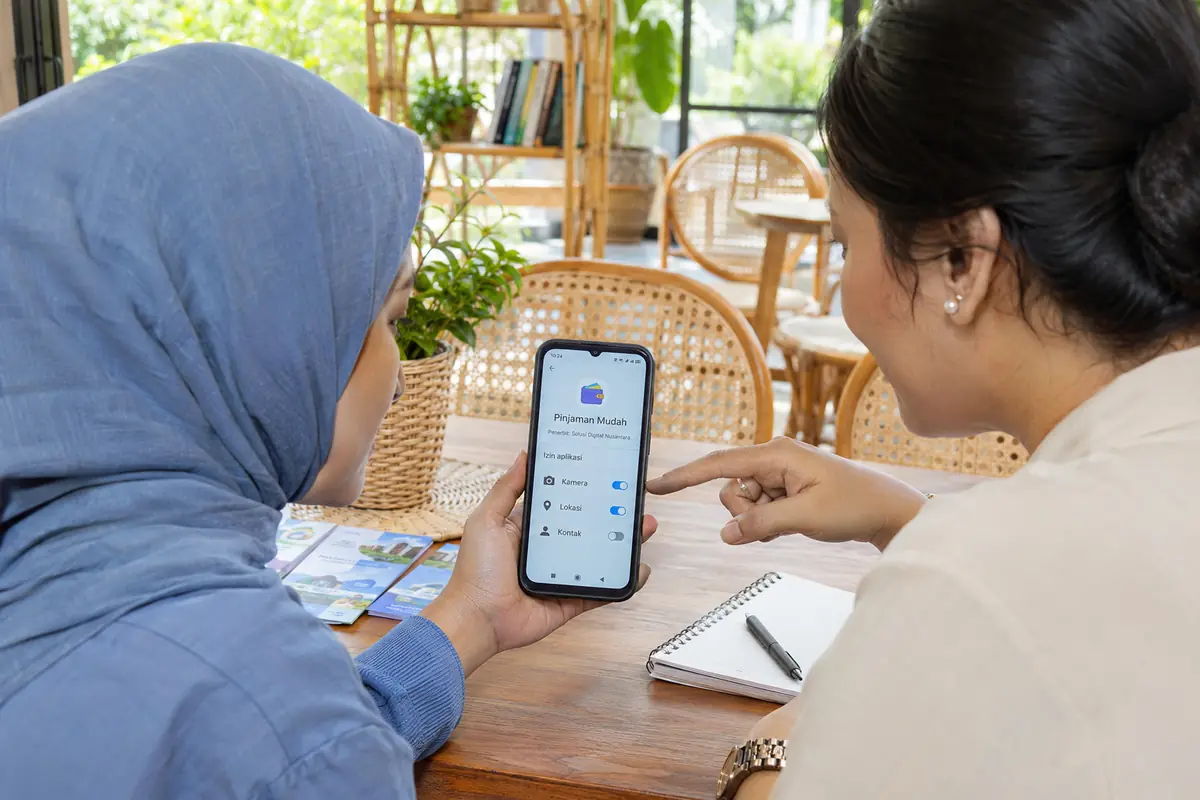
In Indonesia, loan app customer support contacts are the official channels through which a borrower can ask questions, report payment problems, dispute charges or file a complaint with a digital lender. They normally include an in-app help menu, a service email address, a telephone or messaging line and a written complaint procedure. Knowing where the genuine channels are matters to anyone who borrows through an app, because a fake number found through a search result or a social media post can lead to fraud instead of help.
Where genuine support channels are listed
The most dependable source is the application itself, opened from an official store, together with the lender's own website. A licensed operator displays its legal company name, address, service email and telephone details in the help or about section, and repeats them in the loan agreement.
Compare these details with the entry for the operator in the register published by the Financial Services Authority. A number that appears only in an advertisement, a forum reply or an unknown messaging profile has not been confirmed by the company. When the lender has a banking partner, the partner's own service line may also be listed for payment and account questions.
Keep the official website address and service number in a personal note from the first day of borrowing. That way, when a problem arises, the borrower does not need to search online, where results can be manipulated by fraudsters.
Information to prepare before making contact
Support teams solve problems faster when the borrower arrives with complete facts. A short, ordered message shortens the exchange and leaves a clear written trail.
- Full name as registered in the app and the registered phone number.
- Loan reference number, date of the agreement and the due date.
- Screenshots of the offer, the repayment schedule and any payment proof.
- A precise description of the problem, such as a double debit, a wrong balance or an unexpected fee.
- The outcome the borrower wants, for example a correction, a refund or a payment plan.
Never send a one-time password, the app login code or a card security number to anyone, even if the person claims to belong to the support team.
Choosing between chat, email, telephone and letter
Chat and phone calls are quick for simple questions such as the outstanding balance, but they leave weaker evidence unless the conversation can be saved. Email is better for disputes, because it records the date, the content and the answer. When the matter involves money, request a written confirmation of any promise made by phone.
Service hours matter as well. Many lenders answer during business hours on weekdays, and some run longer hours. If a due date falls near a weekend or holiday, contact the lender early rather than on the last day.
Common reasons borrowers contact support
Typical requests include confirming the balance, correcting a payment that was not recorded, asking for a restructured schedule after income falls, disputing a late charge and requesting deletion of personal data after repayment. Each of these has a different best channel and different supporting documents.
For a payment not credited, the transfer receipt and the account number used are the key evidence. For a charge dispute, the agreement and the cost statement shown at the time of acceptance are the reference. For collection behavior, dates, phone numbers and recordings of calls are valuable.
Filing a formal complaint with the lender
Financial service providers under OJK supervision must provide a way to receive and settle consumer complaints, and they must acknowledge and handle them within deadlines set in the regulation. A formal complaint is more effective than a casual message because it enters an internal register. Keep the tone factual and avoid threats or insults, which tend to slow down the handling.
State the facts in a calm and concise manner, attach the documents and ask for a written reply. Keep the complaint number and the date of submission. If the lender replies late, rejects the complaint without reasons or does not reply at all, the borrower has the basis to escalate.
Escalating to OJK and other bodies
The consumer contact service of OJK can be reached on 157 and through a messaging number and email listed on its website, and complaints can also be submitted through the consumer protection portal. OJK asks that the complaint has first been submitted to the financial institution, so the lender's reference number is helpful.
Disputes that remain unresolved can be taken to an alternative dispute resolution institution for the financial services sector, which offers mediation and arbitration without the cost of a court case. Problems with e-wallets or payment services can also be raised with Bank Indonesia, whose contact center is reachable on 131. Threats, extortion or the spread of personal data should additionally be reported to the police.
Keeping records and following up
Every contact should leave a trace. Save chat transcripts as screenshots, note the date, time and name of the agent for phone calls, and keep copies of emails together with the loan agreement in a single folder on the phone or computer. If an agent promises a correction, ask for the expected date and for a reference number for the request.
Follow up politely when the promised date passes. A short message quoting the earlier reference and the date of the first contact is usually more effective than opening a new request, because it links the earlier history. Borrowers who have kept their records can show exactly what was said, what was paid and when each step took place, which makes any later escalation faster and harder to dismiss.
Also review the account after the matter is closed. Confirm that the balance, the due dates and the status in the app match the answer received, and ask for written confirmation that the loan is fully paid when the final installment has been made. That confirmation can be important when applying for credit in the future.
Avoiding fake support scams
Fraudsters often monitor social media for complaints and reply with a friendly offer to help from a fake account. They then ask for passwords, codes or an advance payment to solve the problem. Other scams publish counterfeit customer service numbers that rank well in online searches.
A real support agent will not ask for a one-time code, a PIN or a transfer to a personal account. Use only the channels inside the official app or those printed in the agreement, and report any account that impersonates the lender.
Frequently asked questions
How can a borrower tell that a support number is real?
Check that it appears in the official app, the lender's own website and the loan agreement, and that the company name matches the register of licensed operators.
What should be sent in a first message to support?
The loan reference, the date, a clear description of the problem, supporting screenshots and the solution requested. Sensitive codes must never be included.
When can a complaint go to OJK?
After the borrower has submitted it to the lender and received no reply or an unsatisfactory one. The consumer service is available on 157.
Can support staff ask for a code to fix an account problem?
No. One-time passwords and PINs are strictly personal, and a request for them is a sign of fraud.
What if the lender is not licensed and has no real support?
Stop paying fees, keep evidence and report the operator to OJK through 157 so that it can be handled as illegal lending.
Further reading
- Bank Indonesia services and consumer complaints : Official central bank page on public services, consumer complaints and the Bicara 131 contact center for payment system questions.